State: Required
Virginia: The Rules Your Auto Policy Must Follow
Virginia raised its minimum limits in 2025, ended the option to pay a fee instead of insuring a car, requires uninsured and underinsured motorist coverage on every policy, and lets you ask the Commissioner to review a cancellation or nonrenewal.
By PolicyBrook Editorial Team Updated 6-minute read
Declarations
Virginia- UM/UIM rule
- Required
- Minimum liability
- 50/100/25
- Insurer cancellation notice
- 45 days (15 nonpayment)
- Nonrenewal notice
- 45 days
In brief
A Virginia policy that took effect on or after January 1, 2025 must carry at least $50,000/$100,000/$25,000 of liability coverage. Uninsured and underinsured motorist coverage is required; you can turn down only the amount above the minimum. After 60 days, an insurer can cancel only for nonpayment, a suspended license or a move out of state, with 45 days' notice (15 days for nonpayment). Nonrenewal needs 45 days' notice, and you have 15 days to ask the State Corporation Commission's Bureau of Insurance to review either one.
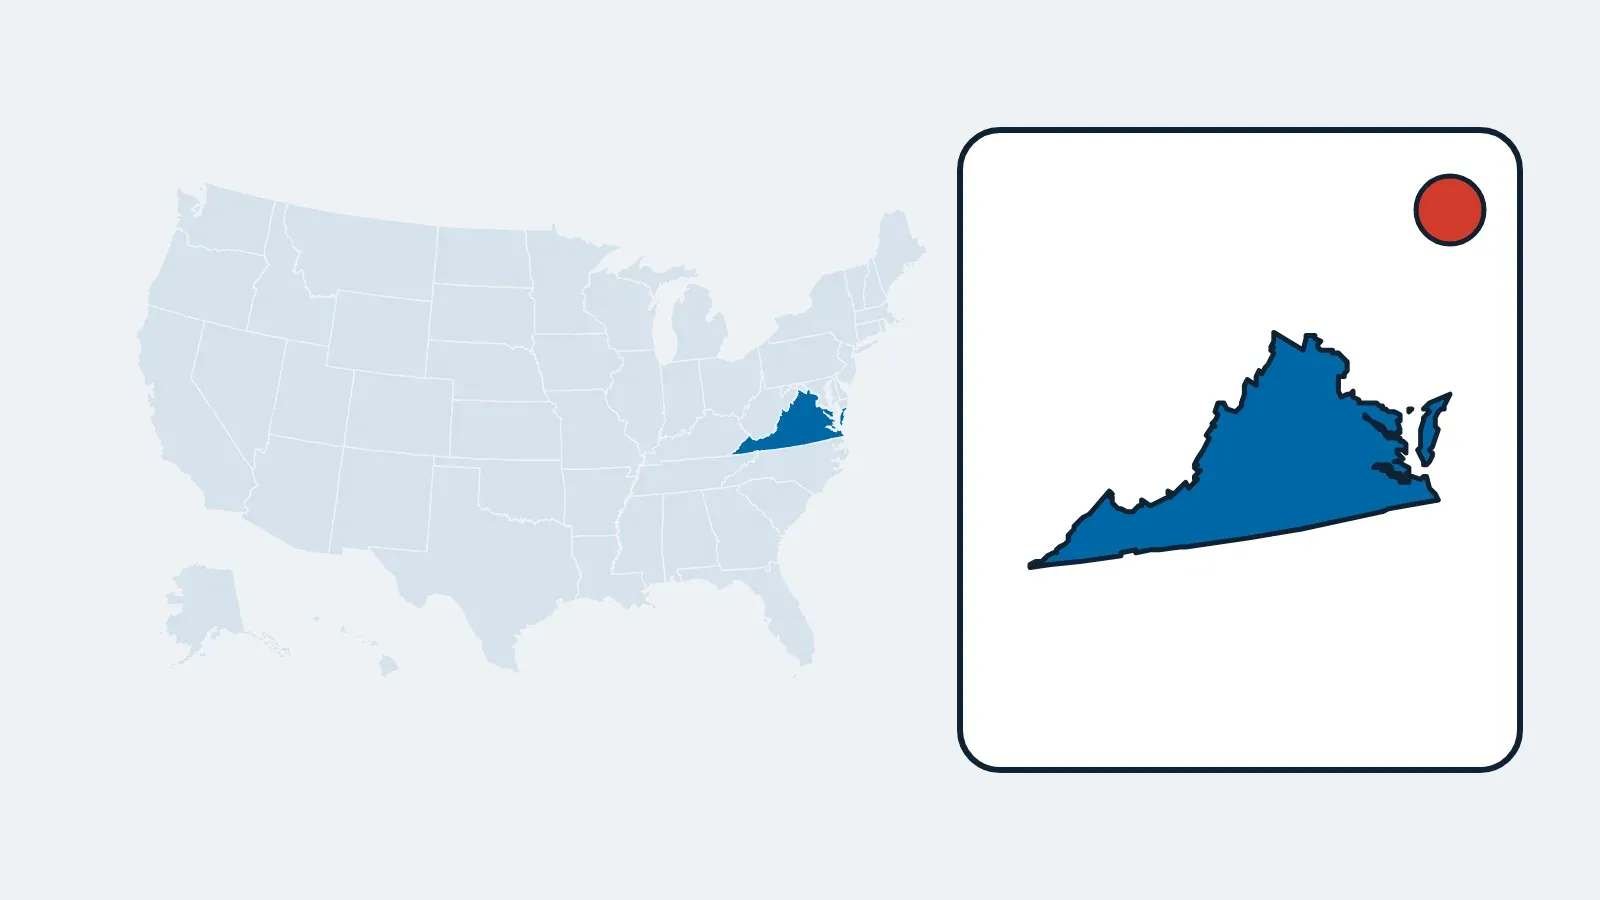
Virginia policy rules
State schedule- UM coverage rule
- Required
- Minimum liability
- 50/100/25For policies effective on or after January 1, 2025; 30/60/20 before
- UM/UIM rule
- Required at least at the minimum limitsDefaults to your liability limits; only the amount above the minimum can be rejected
- Insurer cancellation notice
- 45 days; 15 days for nonpaymentAfter 60 days, only for nonpayment, a suspended license or a move out of state
- Nonrenewal notice
- 45 daysAsk the Commissioner for review in writing within 15 days of receiving the notice
- Regulator
- State Corporation Commission, Bureau of Insurance
Minimum limits on a Virginia policy
Section 46.2-472 of the Code of Virginia sets the minimums. For policies effective on or after January 1, 2025, they are $50,000 for one person's injuries, $100,000 for all injuries in one accident, and $25,000 for property damage. Policies that took effect from 2022 through 2024 used 30/60/20.
Since July 1, 2024, every vehicle registered in Virginia must be insured at these limits. The Virginia DMV announced that the option to pay an uninsured motor vehicle fee instead of buying a policy ended on that date. If you used to pay the fee, you now need a policy. Use the limits gap worksheet to see how far 50/100/25 goes in a larger crash.
UM/UIM is required on every Virginia policy
Under Section 38.2-2206, a liability policy on a car garaged or used in Virginia must include both uninsured and underinsured motorist coverage. Bodily injury UM limits must be at least the Section 46.2-472 minimums, and UIM limits equal your UM limits.
- Default limits: unless the named insured rejects the extra amount, UM/UIM matches your liability limits.
- What you can reject: the statute speaks of rejecting the additional coverage above the minimum. A rejection by one named insured binds everyone on the policy.
- How UIM pays: by default it pays without a credit for the at-fault driver's liability coverage. A named insured may sign an election to reduce UIM payments by that coverage.
Read Part C before you lower your UM limits or sign an election form.
When a Virginia insurer can cancel your policy
Section 38.2-2212 does not apply to a new policy that has been in force less than 60 days when the notice goes out. After that, an insurer may cancel the coverage Virginia requires only for these reasons:
- The driver's license of the named insured, or of someone in the household or who customarily drives the car, is suspended or revoked during the policy period (or, for a renewal, in the 90 days before it took effect).
- You do not pay the premium or an installment.
- You tell the insurer you have moved your legal residence to another state and the car will be garaged there.
The notice must be mailed or delivered at least 45 days before the cancellation, or at least 15 days when the reason is nonpayment. Section 38.2-2208 lets insurers send it by mail with proof of mailing, such as certified mail or a postal certificate of mailing, or electronically if they keep evidence of transmittal. Neither section sets a refund formula, so the policy's own terms decide how unearned premium is returned; the cancellation refund worksheet helps you check the figure.
Renewal, nonrenewal and Commissioner review
A Virginia insurer must also give 45 days' notice before it refuses to renew. Section 38.2-2212 lists factors that cannot be the only reason, including your age, sex, residence, race, marital status, lawful occupation (military service included), lack of driving experience, and accidents or convictions more than 48 months old. Some uninsured motorist, medical expense, comprehensive and towing claims are also protected.
- Note the date you received the notice. Your 15 days to ask for a review start then.
- Write to the Bureau of Insurance at the State Corporation Commission, with a copy of the notice, if you think the reason or the notice is wrong.
- Shop in parallel. A review does not guarantee the policy continues; see nonrenewal for the steps.
Policyholder questions
Can I drop uninsured motorist coverage in Virginia?
Not entirely. UM and UIM are required at least at the state minimum limits. The named insured can reject only the amount above that floor.
Can I still pay a fee instead of buying insurance in Virginia?
No. The uninsured motor vehicle fee option ended on July 1, 2024. Every registered vehicle now needs a policy that meets the minimum limits.
How do I challenge a Virginia cancellation or nonrenewal?
Send a written request for review to the Commissioner of Insurance within 15 days after you receive the notice. Coverage stays in force while the review runs, unless the reason is nonpayment.
Sources
- Code of Virginia § 38.2-2208 — Proof of mailing or delivery of cancellation and nonrenewal notices
- Virginia DMV — New laws take effect July 1, 2024 (end of the uninsured motor vehicle fee)
- Code of Virginia § 38.2-2212 — Cancellation or refusal to renew motor vehicle policies (2025 edition, via Justia)
- Code of Virginia § 38.2-2206 — Uninsured and underinsured motorist coverage (2025 edition, via Justia)
- Code of Virginia § 46.2-472 — Minimum liability limits (2025 edition, via Justia)
Facts on this page were checked against these sources on November 15, 2026. Virginia raised its minimum limits to 50/100/25 for policies effective on or after January 1, 2025, and ended the uninsured motor vehicle fee on July 1, 2024.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.