State: Required
Illinois: The Rules Your Auto Policy Must Follow
Illinois requires uninsured motorist coverage on every auto liability policy, sets 25/50/20 minimum limits, and limits why an insurer may cancel once a policy is 60 days old. Here is how those rules shape your policy.
By PolicyBrook Editorial Team Updated 5-minute read
Declarations
Illinois- UM/UIM rule
- Required
- Minimum liability
- 25/50/20
- Insurer cancellation notice
- 30 days (10 nonpayment)
- Nonrenewal notice
- 30 days
In brief
An Illinois policy must carry liability limits of at least $25,000/$50,000/$20,000 and uninsured motorist bodily injury coverage, which the law does not let you drop. If you buy UM limits above the minimum, underinsured motorist coverage must come with them. After 60 days in force, an insurer may cancel only for listed reasons, with 30 days' notice (10 days for nonpayment), and it must give 30 days' notice with a specific explanation before it refuses to renew. The Illinois Department of Insurance hears cancellation appeals and complaints.
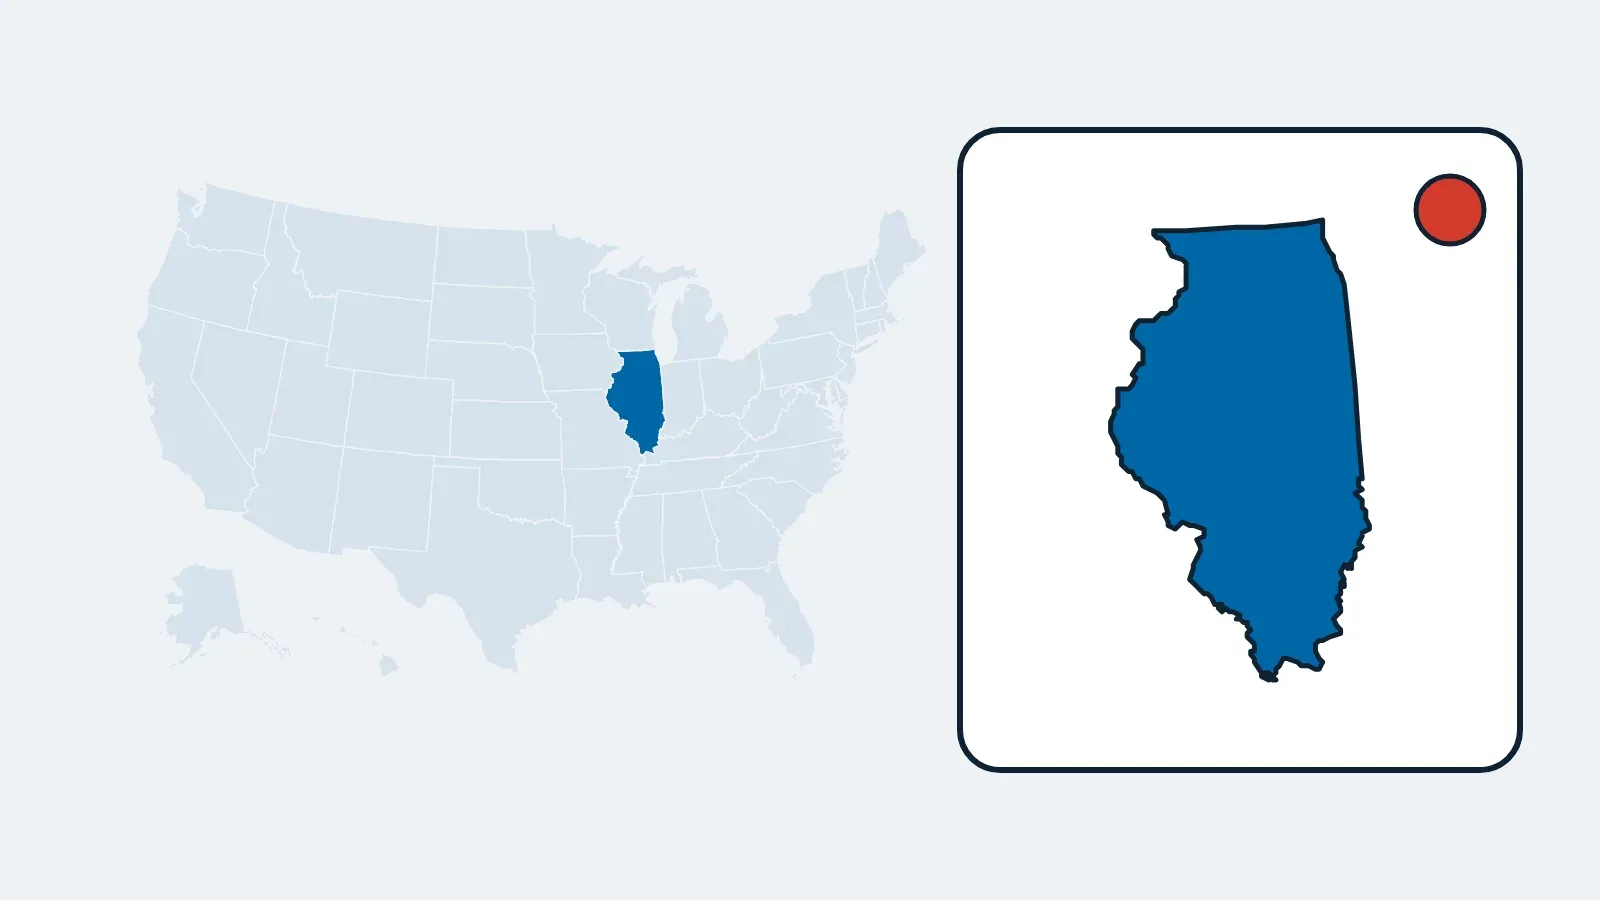
Illinois policy rules
State schedule- UM coverage rule
- Required
- Minimum liability
- 25/50/20
- UM/UIM rule
- UM bodily injury required, at least 25/50UIM required when UM limits exceed the minimum; UM property damage is optional
- Insurer cancellation notice
- 30 days; 10 days for nonpaymentAfter 60 days in force, only for listed reasons; appeal to the Department at least 20 days ahead
- Nonrenewal notice
- 30 daysNotice must give a specific explanation of the reasons
- Regulator
- Illinois Department of Insurance
Minimum limits on an Illinois policy
The Illinois Department of Insurance lists the liability floor, from section 7-203 of the Illinois Vehicle Code, as $25,000 for injury to one person, $50,000 for all injuries in one accident, and $20,000 for property damage. That is the lowest Part A limit an Illinois declarations page may show, written 25/50/20. The department notes that these amounts may not fully protect you if you are sued; the limits gap worksheet shows what a larger crash could leave you owing.
Uninsured motorist coverage is mandatory
Under 215 ILCS 5/143a, an auto liability policy for a car registered or principally garaged in Illinois cannot be issued or renewed without uninsured motorist bodily injury coverage, at limits at least equal to the Vehicle Code minimums of $25,000 per person and $50,000 per accident. The statute gives the named insured no way to reject that core coverage, which is why Illinois is marked "Required" on the state rules map.
Two related coverages work differently. Under section 143a-2, if you buy UM limits above the minimum, your policy must also carry underinsured motorist coverage. Uninsured motorist property damage coverage is optional: no written rejection is needed, and a policy that shows no premium for it is treated as your choice not to buy it. See Part C for what each pays.
| Coverage | Rule | Statute |
|---|---|---|
| UM bodily injury | Required, at least 25/50 | 215 ILCS 5/143a |
| Underinsured motorist | Required when UM limits exceed the minimum | 215 ILCS 5/143a-2 |
| UM property damage | Optional; no written rejection needed | 215 ILCS 5/143a |
When an Illinois insurer can cancel
The Department of Insurance explains that during a new policy's first 60 days, an insurer may cancel for almost any reason. Once the policy has been in force 60 days, or if it is a renewal, cancellation is limited to a list of reasons, including:
- You do not pay the premium by the due date.
- The policy was obtained through misrepresentation or fraud, or you violated its terms.
- When asked on the application, you did not fully disclose accidents and moving violations from the past 36 months.
- Someone made a fraudulent claim or knowingly helped another person make one.
- A driver's license was suspended or revoked in the past 12 months, or a driver has certain convictions or a record or condition that endangers the public.
- The car is unsafe, carries passengers for hire, hauls flammables or explosives, or failed a required inspection.
An insurer may not cancel solely because of claims arising from a hate crime that a police report identifies as one. The notice must be in writing, explain the reason, tell you about your right to appeal and your possible eligibility for the Illinois Automobile Insurance Plan, and be mailed to your last known address at least 30 days before the cancellation date, or at least 10 days before for nonpayment.
Renewal and nonrenewal in Illinois
Section 143.17 of the Insurance Code requires an insurer that will not renew a personal auto policy to mail at least 30 days' advance notice that includes a specific explanation of the reasons. The rule does not apply when the company has offered to renew. If the insurer skips the required notice, the policy does not simply end: it stays in force until you buy similar coverage elsewhere.
The same section requires a company that changes deductibles or coverage across a line of business to mail written notice at least 60 days before the renewal date. Compare a renewal declarations page with the old one line by line; see policy renewal.
How to appeal or complain in Illinois
- Read the notice. Check the reason, the mailing date and the effective date against the rules above.
- Appeal at least 20 days before the cancellation date if the reason is not nonpayment. Mail or deliver a written request to the Illinois Department of Insurance that explains in detail why the cancellation is improper; if a hearing is granted, you get written notice of its date and time.
- File a complaint through the department's website, idoi.illinois.gov, for nonrenewals and other disputes.
- Arrange new coverage anyway so you are not uninsured on the effective date; see lapse and reinstatement.
Policyholder questions
Can I reject uninsured motorist coverage in Illinois?
Not the core bodily injury coverage. Illinois requires it on every auto liability policy at 25/50 or more. Uninsured motorist property damage coverage is optional.
Can an Illinois insurer cancel my policy after a claim?
After 60 days, only for a reason the law lists, such as a fraudulent claim. Claims from a hate crime identified in a police report cannot be the sole reason.
How much notice do I get before an Illinois nonrenewal?
At least 30 days, by mail, with a specific explanation of the reasons. Without the required notice, the policy continues until you buy similar coverage.
Sources
- 215 ILCS 5/143a — Uninsured motor vehicle coverage
- 215 ILCS 5/143.17 — Notice of intention not to renew
- Illinois Department of Insurance — If your auto insurance policy is canceled
- Illinois Department of Insurance — Auto insurance shopping guide
- 215 ILCS 5/143.13 — Definitions, policy of automobile insurance (via FindLaw)
Facts on this page were checked against these sources on November 15, 2026. Illinois is one of the states where uninsured motorist bodily injury coverage cannot be rejected.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.